PoppitsBoard meeting · 4 November 2026
Download the brand guidelines (PDF)
Poppits logo
Board meeting
Jack O'Neill, CEO
4 November 2026
Agenda
What we learned, what it means for Poppits, what it costs, what we ask
1
Executive summary
3 min
2
The research and the companies we learned from
9 min
3
Poppits: the business, its challenges, the metrics
11 min
4
Why the plan is built this way, and how the company is run
10 min
5
The financials: three cases and the cash they need
14 min
6
The ask and the proof gates
3 min
7
What is built, blockers, the next 30 days
9 min
1
Poppits logo
Executive summary
Base plan performance: headline numbers
Base case · households by October 2029
15,600
Kids' households, reported basis
Base case · revenue and EBITDA in 2029
$2.24M
EBITDA $324k, positive every month from Aug 2027
Base case · cash needed
$175k
$56k now; $119k after the March read
Upside · revenue and EBITDA in 2029
$10.69M
EBITDA $3.27M; it needs about $387k, earlier
Customers who come back decide who wins
The winners earned trust and a repeat habit
The failures lost their customers, not their marketing
Our challenge is a small, low-priced basket
The plan answers it; the first renewal is the number that matters
Fund the proof now; the rest after the March 2027 read
2
Poppits logo
The research
110 research reports and about 2,900 sources stand behind the plan
Market analyses completed
16
Parents are moving to fluoride-free: 5.4% of US toothpaste sales, up from 3.9%
Comparable company analyses
14
The failures lost customers, not marketing battles
Product, supply and cost analyses
12
Unit cost falls with bigger batches and better sourcing, not with sales alone
Growth and channel analyses
26
Referrals, creators and retention are proven methods; our own rates are untested until launch
Compliance and claims analyses
37
We may say fluoride-free, cleans and freshens; not cavity prevention. All 50 states reviewed
Funding analyses
5
Comparable brands raised big rounds only after they had proved demand
Each number is the count of research reports in that group, 110 in all. Every figure in the research is labelled verified, reported or estimate and carries its source.
3
Poppits logo
The companies we learned from
Fifteen companies: five acquired, three went public, four private, three failed
Oral care
Failed
hello logo
Sold to Colgate, 2020
$351M
Bite logo
Private
Boka logo
Sold to Heyday, 2022
Quip logo
Private
raised $160M+
Subscription personal care
Dollar Shave Club logo
Sold to Unilever, 2016
about $1B
Harry's logo
Private
valued at $1.7B
Billie logo
Sold to Edgewell, 2021
$310M
Hims & Hers logoHims & Hers logo
Went public, 2021
about $1.6B
Kids, family and beauty
Lovevery logo
Private
about $800M
Once Upon a Farm logo
Went public, 2026
about $811M
Honest logo
Went public, 2021
$1.44B
Hero Cosmetics logo
Sold to Church & Dwight
2022, $630M
Blue Apron logo
Sold for about $103M, 2023
after a $300M IPO
Casper logo
Taken private, 2022
about $286M
Hello Bello logo
Chapter 11, 2023
Private values are funding-round valuations, not exits. Logos for board use only.
4
Poppits logo
What made them win
Winners earned trust, a repeat habit and demand a bigger buyer wanted
A brand with one clear reason to switch
Named one problem plainly
Billie, Dollar Shave Club
Led with one hero product
Hero
Protected parent trust
Lovevery, Once Upon a Farm
A business built on customers who come back
Earned the refill habit first
Hims & Hers
Entered retail only after proof
Hero, Billie
Controlled cost before scaling
Harry's; Hello Bello did not
Demand a larger buyer wanted
Sold to the leader in their aisle
Colgate, Edgewell, Church & Dwight
Proved demand a buyer could scale
Hero
Valued on proven sales
Hero at 5.5x sales
5
Poppits logo
What sank the others
The failures did not lose on marketing; their customers did not come back
Blue Apron
−28%
Customers lost in one year, 2017
Casper
23%
Of direct customers were repeat buyers, 2019
Hello Bello
Ch. 11
Bankrupt in 2023, sunk by cost and stock
The lesson: retention, not marketing spend, separated the winners from the losers.
6
Poppits logo
Why Poppits
Poppits starts with four advantages
1 · A habit becomes a subscription
Brushing happens every day
One supply is a month of gel; it renews every two months.
2 · A clear reason to switch
Clean teeth, minus the mess
One gel, no tube, no waste; a sink that stays clean.
3 · Order value can grow
One box, the whole family
More children, the parent, the adult product; all in the same shipment.
4 · A second channel that fits
Hotel packs add volume
Volume lowers the cost of every supply, with no new acquisition spend.
The winners earned a repeat habit, gave a plain reason to switch and widened the basket; Poppits is built to do the same.
7
Poppits logo
Poppits today
A small, low-priced basket creates four challenges
The business
A month of gel for one child
65 gels a supply
$9.99 a supply
A subscription every 2 months
Our own site first
Then creators, ads, Amazon
300 founding boxes
Pre-ordered in December, shipped mid-January
C1 · Small basket
$19.98 −$0.83
A typical order; the first subscription order loses money, a renewal earns about $5.20
C2 · Unit cost
$3.08 → $1.84
Cost to make a supply, small batch to large
C3 · Shipping
$7.97
To ship a first order
C4 · Marketplace fees
35%
Amazon's share of a $24.99 kit
Costs are estimates and assumptions until supplier quotes arrive.
8
Poppits logo
The metrics
One chain of metrics runs the company, from each shipment to the cash we need
Contribution per shipment
What each shipment earns after its costs
Retention
Who stays, led by the first renewal
→
Household value
What a household earns us over 24 months
Acquisition cost
What it costs to win a household
→
The spending test
Value at least 1.5x cost, or spend stops growing
→
Growth and cash
How fast we grow sets the cash we need
Marketing as a share of revenue is the second number we report. Emerging consumer brands typically spend 10 to 15% of revenue, up to 20 to 25% while launching. Base plans 31% in year 1, falling to 24% by 2029; Upside 23% falling to 17%.
9
Poppits logo
Our levers
We control price, shipping and channels; we have to learn the renewal rate
Metric
We control
We have to learn
Contribution per shipment
Price, shipment size, shipping
Real cost quotes
First renewal
The offer, payment recovery
The rate: 55% assumed
Subscription take-up
Free container, kit first
The rate: 25% assumed
Acquisition cost
Channel mix
Cost by channel at volume
Value ÷ cost
The 1.5x spending rule
Whether it holds
10
Poppits logo
Why the plan is built this way
Each challenge has a designed answer and a metric that tracks it
Challenge
Our answer
Metric
C1 Small basket
Subscription; the kit as first order; the adult product in the same box
Order value
C2 Unit cost
Large batches that sell within 9 months; hotel volume counts toward supplier savings
Cost per supply
C3 Shipping
Flat refill envelopes; a fulfilment partner at scale
Postage per order
C4 Marketplace fees
Amazon for discovery, kits only
Amazon margin
11
Poppits logo
Beyond the kids' refill
The adult product raises order value; hotels are a modest paying customer
Adult product · April 2027
Same household, same box
Kids' subscribers add it; one order, one postage
Hotels · from mid-2027
A wrapped two-gel pack at about $0.90
Bought the way hotels buy amenities, mostly on request
Independent retail · off
An option, not the plan
Modelled as a switch so the board can see it
Base case
Adult product
Hotels
Retail (if on)
Share of revenue, 2027 to 2029
12%
19%
about 12%
Acquisition spend it needs
None: existing households
Two signings a month
Faire fees and testers
What it does to the plan
Order value up
Gel volume up, cost per supply down
Not in the plan
The upside case adds one airline contract from January 2028; it is upside only.
12
Poppits logo
How the company is run
A founder, in-house AI systems and a fulfilment partner; people for the work that stays human
The founder, and the people added for work that stays human
Customers and care
Answers, renewals, failed payments and reviews handled by the care system; every reply checked against the claims rules.
A person signs off refunds and any complaint.
Supply and fulfilment
Stock, reorders and batch timing planned by the supply system; the fulfilment partner packs and ships.
A person places every supplier order.
Growth and content
Creator outreach, ad tests and content drafted and measured by the growth system against the spending rule.
A person approves every spend and every post.
Fulfilment partner: packs and ships from 300 orders a month
Nothing is sent, published, spent or promised without a named person saying yes.
End of 2029
Households
People
People a month
AI and platform a month
Floor
4,442
0.5
$2,200
$1,979
Base
16,384
2
$10,450
$5,964
Upside
73,324
3
$24,200
$14,002
People exclude the founder. AI and platform is tokens and software tiers, built and maintained in house.
13
Poppits logo
The financials
Three cases: revenue, profit and the cash each needs
$000
Floor
Base
Upside
Net revenue FY2027
177.3
421.7
1,293.5
Net revenue FY2028
309.0
1,338.4
5,410.4
Net revenue FY2029
486.2
2,240.3
10,691.0
EBITDA FY2027
(56.3)
(0.7)
54.6
EBITDA FY2028
(1.9)
139.4
1,199.6
EBITDA FY2029
(2.0)
324.1
3,273.7
EBITDA positive every month from
Sep 2029
Aug 2027
Aug 2027
Peak cash need
151.4
174.8
387.4
Fiscal years run November to October; FY2027 is the first year of sales. Upside is an illustrative upside: what it looks like if it works.
14
Poppits logo
Income statement · Base case
Base case income statement, FY2026 to FY2029
$000
FY2026 (Nov-Dec)
FY2027
FY2028
FY2029
Net revenue
0.0
421.7
1,338.4
2,240.3
Growth %
n/m
n/m
217%
67%
Cost of goods sold
0.0
(108.4)
(293.9)
(464.2)
Gross profit
0.0
313.3
1,044.5
1,776.1
Gross margin %
n/m
74%
78%
79%
Fulfilment and selling
0.0
(140.7)
(424.0)
(707.1)
Contribution
0.0
172.5
620.5
1,069.0
Marketing
(2.3)
(132.8)
(358.1)
(543.1)
Contribution after marketing
(2.3)
39.7
262.4
525.9
Operating expenses
(6.0)
(40.4)
(122.9)
(201.8)
EBITDA
(8.3)
(0.7)
139.4
324.1
EBITDA margin %
n/m
0%
10%
14%
Net income
(8.3)
(0.7)
139.4
324.1
Costs in parentheses. No debt, no asset purchases, and no income tax at company level (LLC).
15
Poppits logo
Cash flow statement · Base case
Base case cash flow, FY2026 to FY2029
$000
FY2026 (Nov-Dec)
FY2027
FY2028
FY2029
Net income
(8.3)
(0.7)
139.4
324.1
Change in inventory
0.0
(65.8)
(113.2)
(19.9)
Change in supplier deposits and receivables
(14.1)
(31.7)
(15.9)
(22.9)
Change in customer deposits
6.0
(6.0)
0.0
0.0
Cash from operations
(16.3)
(104.2)
10.3
281.3
Equity raised (the staged ask)
56.3
118.5
0.0
0.0
Net change in cash
40.0
14.3
10.3
281.3
Opening cash
24.0
64.0
78.3
88.6
Closing cash
64.0
78.3
88.6
369.9
Opening cash $24,000. Balance sheet in the appendix.
16
Poppits logo
The three cases
What has to be true in each case, and what each produces
Floor
Base
Upside
Founding boxes
100
200
300 + 150
Paid ads start at, per household
$30
$20
Costs 25% below Base
First orders that subscribe
25%
25%
40%
Viral moments
None
Averaged in
Two, 2,500 households each
Amazon, units a month in its first year
180
360
720, then +10% a month
Marketing spend grows 12% a month while the 1.5x test passes, up to
$36k
$60k
$90k
Hotels
Never land
Two a month; one stay in five
Four a month; an airline from 2028
Active households, October 2029
4,442
15,567
66,480
Net revenue, FY2029
486.2
2,240.3
10,691.0
EBITDA, FY2029
(2.0)
324.1
3,273.7
EBITDA positive every month from
Sep 2029
Aug 2027
Aug 2027
Peak cash need and month
151.4, May 2029
174.8, Oct 2028
387.4, Feb 2028
Marketing caps are paid and creator spend together. The renewal curve is the same in every case: 55% at the first renewal. Upside is illustrative: what it looks like if it works.
17
Poppits logo
Where the growth comes from
In every case most households come from our own site and Amazon; hotels are an addition
Floor
3k
4k
1k
62%
36%
8k
Base
13k
11k
3k
54%
21%
18%
30k
Upside
38k
63k
45%
25%
21%
10%
127k
New households, 2029:
Paid ads
Amazon
Creators
Referrals
Word of mouth
Viral moments
Revenue mix, 2029:
Own site, kids
Amazon
Hotels
Adult, own site
New households won in FY2029 by source, and the revenue mix that year. Marketing is 17% of revenue in the upside and 24% in Base.
18
Poppits logo
The cash to get there
Where cash bottoms out in each case, and what moves it
Cash before funding, $000
Floor
Base
Upside
-200-1000100200300400$4,000 reserveMarch 2027 proof readNov 2026Dec 2027Dec 2028Dec 2029Floor -123Base -142Upside -319Upside rises to $3.8M by Dec 2029 (off the chart)
What moves the Base need (±20% on an input; hotels late or small)
Effect on the need
Subscription price
±$176k
Paid acquisition cost
±$163k
Subscription take-up
±$58k
Ingredient cost
±$51k
First renewal rate
±$47k
Hotels three months late
+$47k
Hotels six months late
+$99k
Hotels and adult at half
+$112k
Kids' product only
+$251k
Floor needs less than Base because the spending rule cuts spend when the economics fail: a smaller company, not a safer one. Upside needs more because the brand is built before subscriptions catch up.
Cash need = the deepest shortfall after the $24,000 on hand, plus a 20% buffer and a $4,000 reserve.
19
Poppits logo
The ask
We have $24k. The base plan needs $175k, in two steps
1
Cash today
$24,000 on hand
November 2026. The founding edition ships in January; production is paid before sales, so cash is below the $4,000 reserve from January 2027.
2
The gap
-$142k at the low point, Oct 2028
The base plan's deepest shortfall before any funding. Add a 20% buffer and the reserve: a cash need of $175k (Floor $151k, Upside $387k).
3
When we need it
$56k now, $119k in April 2027
The proof budget carries months 1 to 5, to the March renewal read. The remainder is released only if the four tests pass.
4
What it is for
Stock, launch marketing, then growth
Now: the founding edition, the first gel batch, the January paid test and creator seeding, the Amazon listing, tools and insurance. April: the next batches as demand doubles, marketing growing 12% a month, the adult and hotel launches and their working capital.
The four proof tests, March 2027
Bar
Model assumes
First renewal
50%+
55%
Subscription take-up
20%+
25%
Value ÷ acquisition cost
1.5x+
1.7x
Cash use vs plan
Within 10%
n/a
The three paths
Now
April 2027
Total
Floor
$46k
$106k
$151k
Base
$56k
$119k
$175k
Upside
$104k
$283k
$387k
The read decides the path, and the remainder is sized to it. Floor and Base need about the same money; the upside needs 2.2 times as much because it grows faster.
Cash need = the deepest shortfall after the $24,000 on hand, plus a 20% buffer and a $4,000 reserve. Upside is an illustrative upside: what it looks like if it works.
20
Poppits logo
What's already built
The plan, the brand and the systems to run Poppits are in place
Product and supply
Supply specified; supplier answers due 6 November
Brand and website
Brand guidelines locked; the Shopify site designed and in build
Compliance by design
50-state review; 105 launch checks
Research and records
110 reports; every decision on record
Operating platform
AI drafts and checks; a named person approves every send and spend
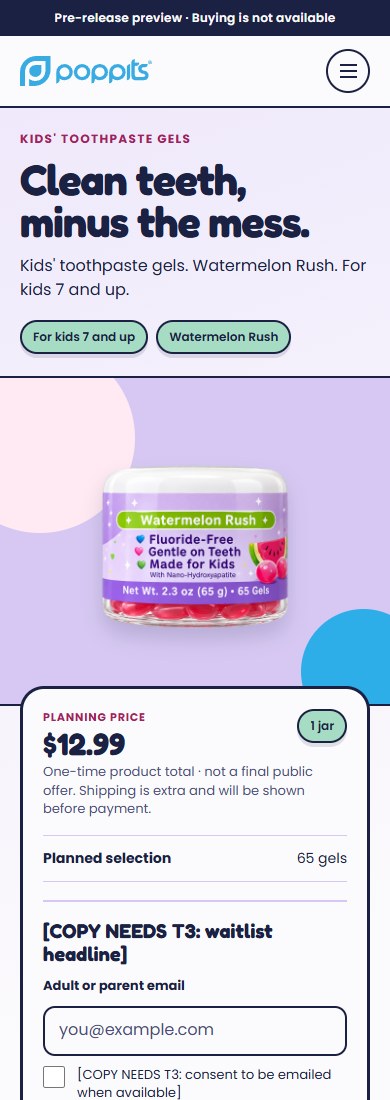
Home
Home, mobile
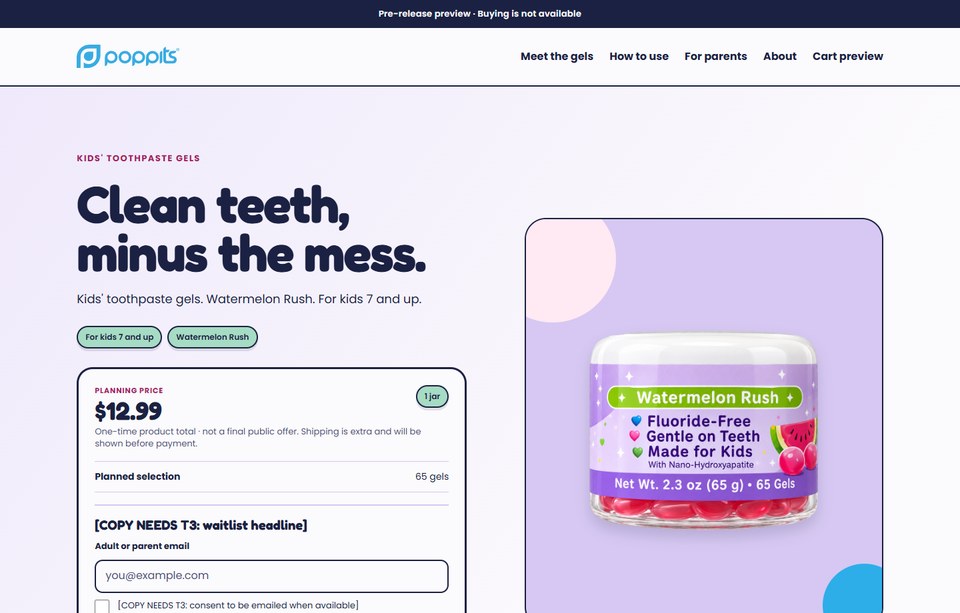
Website prototype, October 2026: the approved design direction, built as a clickable preview before the Shopify build.
21
Poppits logo
The brand
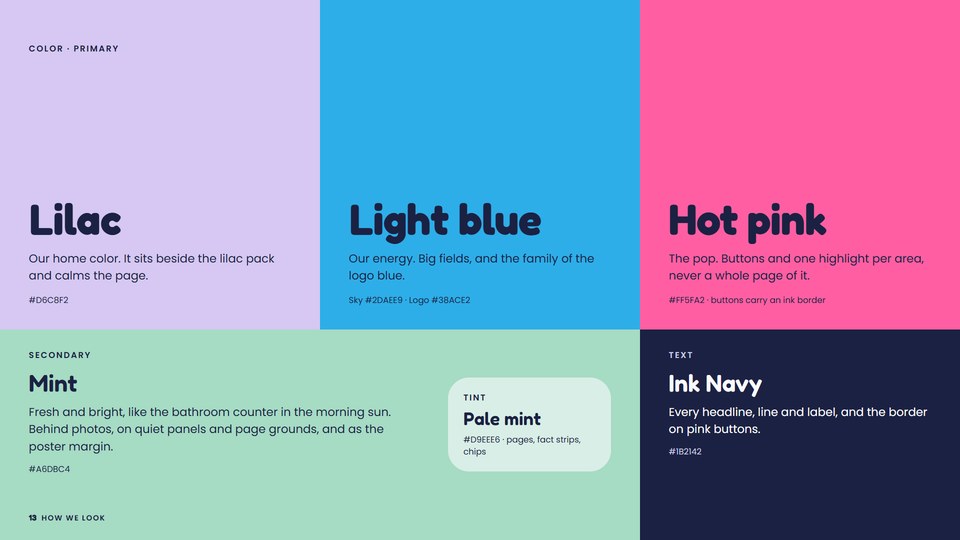
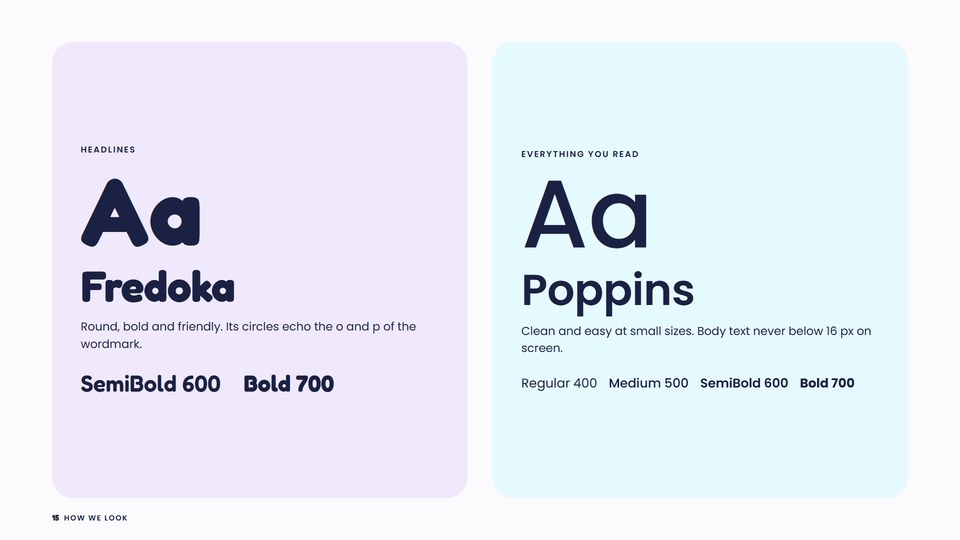
One brand book runs every page, pack and post
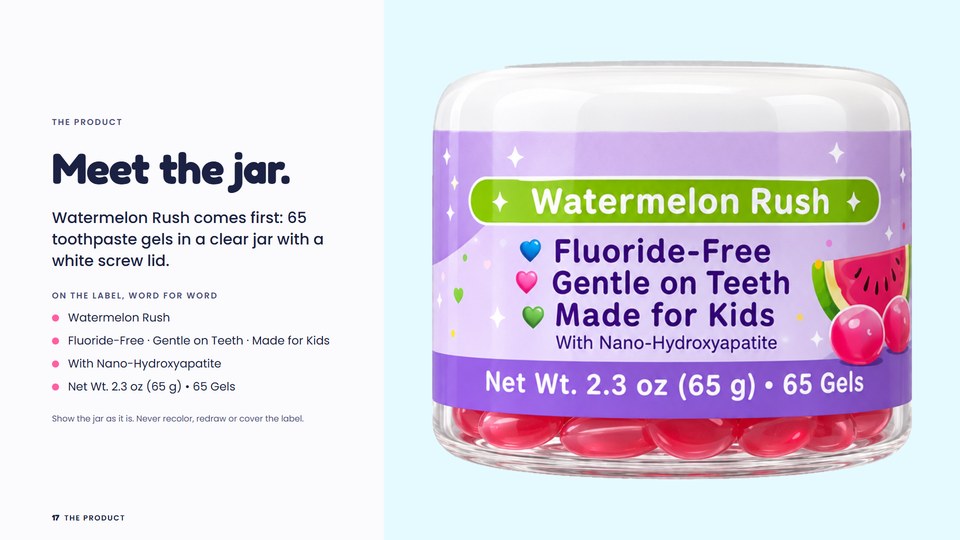
Six of the 33 pages: who we are, how we look, the product, imagery and applications.
22
Poppits logo
The advisory council
Sixteen advisory roles, built to challenge every major decision with evidence
A bench of expert perspectives
Across the 16 disciplines a consumer brand needs
Built from public research, then tested
Two independent reviews each
The council advises; people decide
Launch
Ju Rhyu
Hero Cosmetics: launch to a $630M sale
Oral care
Craig Dubitsky
Founded hello, sold to Colgate
Retail
John Foraker
Ran Annie's; now CEO of Once Upon a Farm
Creative
Mike Cessario
Founded Liquid Death
Growth evidence
Byron Sharp
Author of How Brands Grow
An internal AI research tool. The people named have no affiliation with Poppits and have not reviewed, endorsed or been consulted on this work.
23
Poppits logo
Blockers and risks
Three items stand between us and launch; two risks decide the plan
Item
Holds up
Next step
Supplier documents
Claims and launch
Supplier call, 6 November
A regulatory reviewer
All customer copy
Appoint one
Saleable stock
January shipments
Release, 14 November
Risk: retention is unproven
Whether growth pays
The four proof tests
Risk: thin cash and team
How fast we grow
The staged ask
24
Poppits logo
Next 30 days
Supplier answers, the reviewed model and the founding pre-order
6 Nov
Supplier answers on price, rate and lead time
14 Nov
Pilot stock released
After review
Reviewed model; the cash plan signed off
November
Packaging quotes, mail test, regulatory reviewer, website build
December
Founding edition pre-order; boxes ship mid-January
The model shown today, independently reviewed, with the cash plan signed off.
25
Poppits logo
Future discussions
One more session to schedule: leadership roles and compensation
Thank you.
26
Poppits logo
Appendix
Balance sheet, the council roster, the case inputs and the benchmarks
Appendix · Balance sheet · Base case
Base case balance sheet, FY2026 to FY2029
$000
FY2026 (Nov-Dec)
FY2027
FY2028
FY2029
Cash
64.0
78.3
88.6
369.9
Inventory
0.0
65.8
179.1
198.9
Supplier deposits and receivables
14.1
45.8
61.7
84.5
Total assets
78.1
189.9
329.3
653.4
Customer deposits
6.0
0.0
0.0
0.0
Paid-in capital
80.3
198.8
198.8
198.8
Retained earnings
(8.3)
(9.0)
130.5
454.5
Total liabilities and equity
78.1
189.9
329.3
653.4
Year-end balances. The balance sheet balances in every month of the model.
28
Poppits logo
Appendix · The advisory council
The other eleven roles
Discipline
Built from
Brand
Emily Heyward
Operations and supply
Laura Romano
Growth economics
Taylor Holiday
Customer economics
Peter Fader
Packaging and product system
Evelio Mattos
Distinctive brand assets
Jenni Romaniuk
Discipline
Built from
Amazon
Jason Boyce
Capital and company-building
Mike Fata
Advertising time horizons
Les Binet
Innovation and portfolio
Eric Ryan
Oral-care evidence
Evidence review, no one person
An internal AI research tool. The people named have no affiliation with Poppits and have not reviewed, endorsed or been consulted on this work.
29
Poppits logo
Appendix · Case inputs
The inputs that differ between the three cases
Demand and growth
Floor
Base
Upside
Founding boxes
100
200
300 + 150
Paid acquisition cost at $6k a month
$30
$20
$15
Creator acquisition cost
Base
Base
25% below Base
First orders that subscribe
25%
25%
40%
Word of mouth, households a month
10
30
40 + 2% of households
Referral rate at maturity
3%
3%
4%
Viral moments
None
10% a year, averaged
2,500 in months 6 and 18
Amazon units, listing month 12
180
360
720
Amazon growth after month 12
4%, then 2.5%
4%, then 2.5%
10% a month
Amazon halo per $1 of own-site first orders
$0.05
$0.15
$0.30
Paid and creator spend caps a month
$24k / $12k
$40k / $20k
$60k / $30k
Hotels and overhead
Floor
Base
Upside
Boutique hotels signed a month
0
2
4
Rooms; stays with a pack
n/a
200; 20%
200; 60%
Anchor hotel group
None
10 properties
15 properties
Airline
None
None
20,000 packs a month from Jan 2028
Hotel packs that become a home customer
0.05%
0.3%
0.5%
People cost steps a month
$2k / $5k / $7.5k
$2k / $5k / $7.5k
$4k / $10k / $20k
AI and platform at 10,000 households
$1.5k
$4k
$8k
Everything else is the same in all three cases, including the renewal curve (55%, 85%, 90%, 96%) and every unit cost.
30
Poppits logo
Appendix · Benchmarks
How the cases compare with a well-launched consumer brand
Benchmark (reported)
Typical
Floor
Base
Upside
Year-1 revenue, a well-launched kids' oral-care brand
$0.5M to $0.85M
$0.18M
$0.42M
$1.29M
Year-1 parent buyers
10,000 to 15,000
3,897
7,800
23,281
Marketing as a share of revenue
10 to 15%; 20 to 25% while launching
51 → 29%
31 → 24%
23 → 17%
Growth, years 2 to 3
50 to 100% a year
74%, 57%
217%, 67%
318%, 98%
Revenue path, years 1 to 3
$0.5-1M, $2-5M, $10M+
$0.2M, $0.3M, $0.5M
$0.4M, $1.3M, $2.2M
$1.3M, $5.4M, $10.7M
Benchmarks are trade-press figures for emerging consumer brands (reported, not verified), used as a yardstick, not a source for any input.
31
Poppits logo